Applying for a Wells Fargo credit card is straightforward when you know the rules, eligibility criteria, and the strengths of each product.
You can use this guide to choose a card, submit a clean application, and manage benefits effectively worldwide, while noting that Wells Fargo issues cards to applicants with a valid U.S. residential address.
Key Application Rules and Recent Updates
A few issuer rules shape your timeline and expectations, and aligning to them prevents unnecessary denials.
Six-Month Rule
You are not eligible for a new Wells Fargo credit card if another Wells Fargo card was opened within the last six months, and this generally excludes the Bilt Mastercard® and Signify Business Cash℠.
Welcome Bonus Policy
Prior language limiting one welcome bonus every fifteen months no longer appears in current terms, yet you should always verify offer wording at application time because issuers update promotions regularly.
Availability and Use Worldwide
You need a U.S. address, an SSN or ITIN, and sufficient income to qualify; however, you can use eligible cards worldwide where the payment network is accepted and where foreign transaction terms allow.
Eligibility Checklist
Approval hinges on baseline criteria that many applicants miss at first glance; therefore, review these points before choosing a card.
- Credit profile showing good to excellent scores near 670 or higher improves approval odds and unlocks stronger terms and offers.
- Legal age of at least eighteen years and the ability to form a binding credit agreement are required for all applicants.
- Verifiable income sufficient to handle monthly obligations signals repayment capacity and supports higher starting limits.
- SSN or ITIN plus a government-issued ID ensures identity verification under banking and credit regulations.
- Physical U.S. residential address is mandatory for issuance, while holding a Wells Fargo deposit account can add relationship context.
Popular Wells Fargo Cards and Core Terms
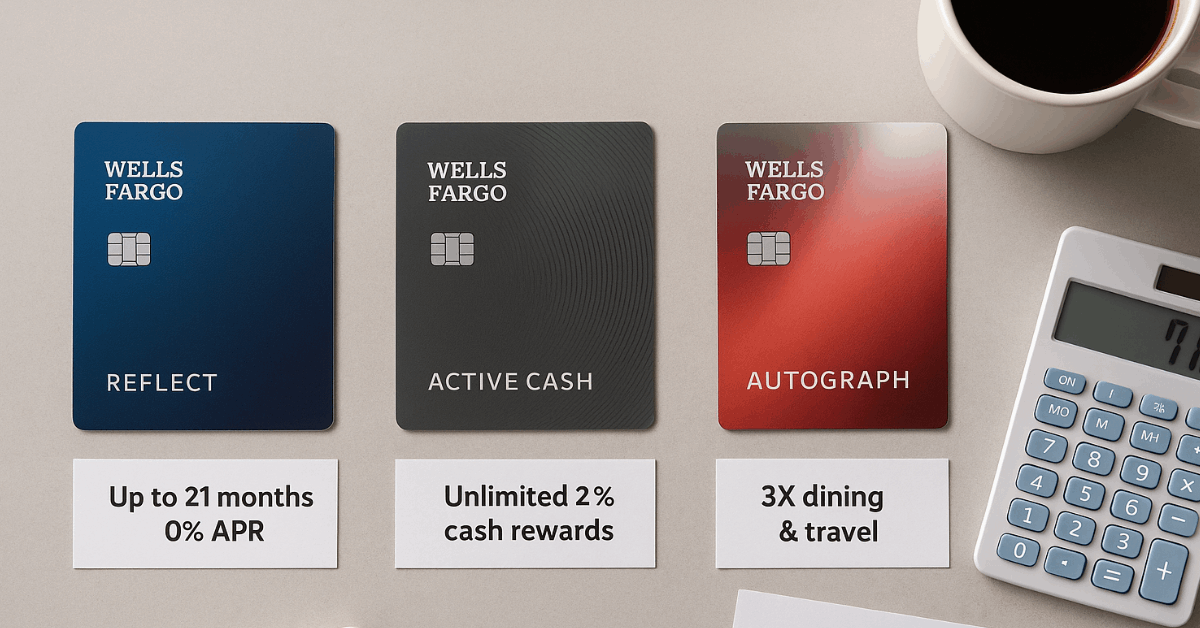
Comparing headline features side-by-side reduces guesswork, which means you match a card to your real spending quickly.
| Card | Welcome Offer | Rewards | Intro APR | Regular APR (Variable) | Annual Fee |
| Wells Fargo Reflect® | N/A | N/A | 0% purchases and qualifying balance transfers for up to 21 months | 17.24%, 23.74%, or 28.99% | $0 |
| Wells Fargo Active Cash® | $200 cash rewards | 2% cash rewards on purchases | 0% purchases and balance transfers for 12 months | 19.24%, 24.24%, or 29.24% | $0 |
| Wells Fargo Autograph® | 20,000 bonus points | 3X on dining, travel, gas, transit, streaming, phone plans; 1X other | 0% purchases for 12 months | 19.24%, 24.24%, or 29.24% | $0 |
| Wells Fargo Autograph Journey℠ | 60,000 bonus points | 5X hotels, 4X airlines, 3X restaurants; 1X other | None | 20.24%, 25.24%, or 29.24% | $95 |
Terms are subject to change; verify current offers at application time. Data reflects issuer details available as of April 30, 2025.
Step-by-Step Application Guide
Small preparation steps prevent avoidable delays, as a result you submit once and move directly to a decision.
- Check your credit scores and reports, then address errors and pay down small balances to lower utilization below thirty percent.
- Compare the Reflect®, Active Cash®, Autograph®, and Autograph Journey℠ against your goals, fees tolerance, and expected categories.
- Select “Apply Now” on the card page, confirm secure connection, and begin the encrypted form on Wells Fargo’s site.
- Enter identity and financial details accurately, including income and monthly housing payment that inform debt-to-income checks.
- Review disclosures, submit, and track status online; some applications finish instantly while others require quick verification.
Boost Your Approval Odds
Minor profile tweaks often shift an application into the approval column.
Credit Profile and Inquiries
You should pause other credit applications for at least sixty days to reduce hard inquiry noise and present a stable profile.
Debt and Documentation
You gain points with under-thirty-percent utilization and clean documentation such as recent pay stubs, bank statements, or tax returns.
Address and Identity Consistency
You avoid manual reviews when your application address matches major documents like a driver’s license or utility bill.
Using Prequalification Effectively
A soft-pull prequalification screen can narrow choices without risking your scores.
How It Works
You enter basic details such as name, address, and the last four of your SSN, or you log in as an existing customer to view targeted offers.
Limits to Expect
You should treat prequalification as an indicator rather than a guarantee, because final approval depends on full underwriting and current terms.
Building Credit After Approval
Good habits turn a new account into long-term credit strength, in turn you protect scores while earning valuable rewards.
- Pay on time every cycle using automatic payments set to at least the statement balance to avoid interest and late fees.
- Keep utilization low by limiting reported balances relative to your credit limit and paying mid-cycle when necessary.
- Use the card regularly for small recurring bills to show active, responsible usage, then redeem rewards consistently.
- Monitor credit reports and FICO® updates in the app to catch errors or fraud and dispute issues quickly.
- Avoid unnecessary new accounts that shorten average age, and keep older lines open to support length-of-history factors.
Common Application Mistakes
Correctable errors cause many denials, and avoiding them keeps your timeline intact.
Ignoring the Six-Month Rule
You risk an automatic decline when applying too soon after opening another Wells Fargo card, so wait until the window fully passes.
Thin or Unverified History
You reduce approvals by applying without established history or sufficient documentation, which underwriters view as higher risk.
Skipping Prequalification
You remove a useful signal when bypassing prequalification, because it helps you target cards aligned to your current profile.
Balance Transfers and Costs to Watch
Strategic transfers can reduce interest meaningfully when you respect fees and timelines.
Transfer Windows and Fees
You typically receive the best transfer fee, often around three percent, when you complete the move within the issuer’s early window such as one hundred twenty days.
APR Transitions
You should mark calendar reminders for promotional end dates, because standard variable APRs can range roughly from seventeen to twenty-nine percent afterward.
Support and Security
Fast help and strong security tools simplify ownership worldwide and reduce fraud exposure.
Contact Channels
You can reach general banking at 1-800-869-3557, the dedicated credit-card line at 1-800-642-4720, international collect at 1-925-825-7600, and rewards assistance at 1-877-517-1358, while secure chat remains available in the mobile app.
Security Practices
You protect data by avoiding public Wi-Fi during applications, enabling alerts for large or international transactions, and using card freeze controls when needed.
Privacy and Protection
You benefit from Zero Liability protection on unauthorized charges when reported promptly, plus EMV and contactless technology that improve checkout security worldwide.
FAQs and Quick Facts
Short factual answers help you plan next steps, that way you avoid surprises after approval.
- What credit limit might you receive initially?
You may see starting lines beginning near one thousand dollars, although your income, credit history, and existing debts can lead to higher limits. - Does Wells Fargo offer student or secured cards now?
You currently will not find a new-applicant secured or student card from Wells Fargo, so consider building history elsewhere if your profile is limited. - Can you prequalify without affecting scores?
You can use the issuer’s prequalification tool for a soft inquiry, and final approval will still require a standard hard pull.
Conclusion
Choosing a Wells Fargo card that matches your spending and payoff style sets you up to earn cash rewards or travel points, manage large purchases through long zero-percent periods, and build credit health worldwide.
You will maximize value by timing applications around the six-month rule, confirming current offers, keeping utilization low, and automating on-time payments every cycle.