Financial emergencies can make quick mobile credit attractive to many Kenyans. This guide explains how mobile borrowing works. It also covers platforms, costs, safety, and regulation.
These points support careful borrowing decisions before accepting short-term mobile credit safely during emergencies.
Why Mobile Credit Has Grown Popular in Kenya?
Phones make mobile borrowing easier to access remotely. Digital convenience reduces reliance on branch applications.
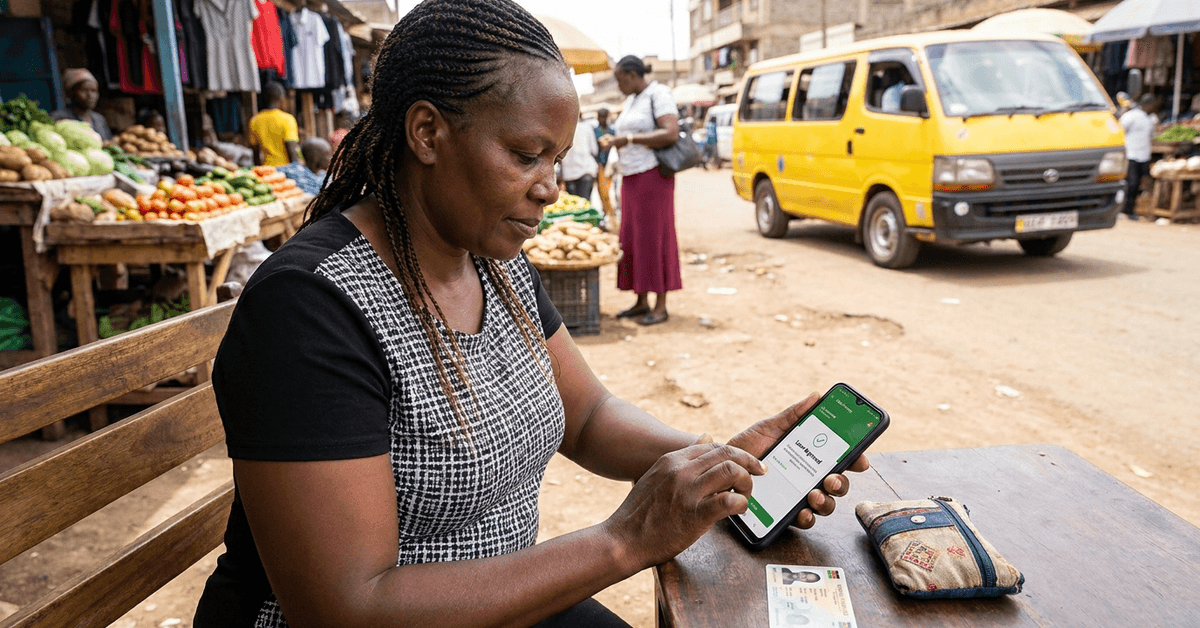
Direct Access, No Formal Collateral
Many mobile credit products require no pledged property. Providers instead use identity data and creditworthiness checks. This can simplify borrowing, although approval is never automatic.
Minimal Paperwork, Rapid Response
Mobile lenders usually use digital forms instead of paper applications. Applicants submit basic verification details through mobile services. Decisions can be fast, though extra checks may delay approval.
Supports Small, Urgent Purchases
Mobile credit can cover transport, medical costs, repairs, or household needs. A modest loan may provide temporary financial flexibility. Borrowers should confirm that repayment fits their budget.
How Does Instant Mobile Credit Work?
Most services follow similar steps from registration to repayment. Exact application requirements differ between providers.
Download and Register on the App
Many lenders operate through apps, websites, USSD, or mobile-money menus. Registration generally requires identity and contact details. Some services connect with M-Shwari for account access.
Verification and Credit Assessment
Providers verify identity before assessing lending eligibility. They may consider transactions, obligations, and credit-reference information. Borrowers should review each provider's privacy and eligibility terms.
Choosing Loan Amount and Terms
Applicants can review available limits, charges, terms, and due dates. Some providers adjust limits using repayment history. Borrowers need not accept the maximum amount offered.
Receiving Funds Instantly
Approved funds may reach a mobile wallet or bank account. Some providers advertise speed, but funding times vary. Borrowers should rely on stated transfer terms.
Top Mobile Credit Platforms in Kenya
Kenya has several digital credit products serving different needs. Each platform has distinct fees, eligibility, and limits.
M-Pesa Fuliza
Fuliza is an M-PESA overdraft, not a conventional personal loan. It supports transactions when wallet balances are insufficient. Charges apply, so repeated use can increase financial pressure.
Tala
Tala provides app-based digital credit to eligible Kenyan customers. Offers depend on current lending criteria. Borrowers should review charges, repayment dates, and privacy terms.
Branch
Branch provides digital personal loans through its mobile platform. Applicants face eligibility and risk assessment. Users should compare total repayment instead of speed alone.
OKash
OKash is another name found in Kenyan digital lending. Its pricing and regulatory status should be verified before applying. Older listings may not reflect current conditions.
Other Notable Apps
Other services include Zenka, KCB M-PESA, Timiza, and additional lenders. Because licences change, verify current official information first.
- Zenka
- KCB M-PESA
- Timiza
- Other CBK-licensed digital credit providers
Key Benefits of Using Mobile Credit in Kenya
Mobile credit can reduce travel, paperwork, and branch waiting. Its advantages include access, speed, and convenience.
Accessibility for All
Mobile services can reach borrowers far from bank branches. Not every phone user meets eligibility requirements. Access depends on the provider and applicant profile.
Speed and Convenience
Applications can often be completed remotely by phone. Digital processing may provide faster lending decisions. Speed should still be weighed against cost and repayment ability.
Gradual Increase in Borrowing Power
Some providers adjust limits after observing repayment activity. Higher limits create greater borrowing capacity. They can also increase debt exposure when borrowing becomes frequent.
No Social Stigma
Mobile applications allow borrowers to request funds privately. This can reduce discomfort around face-to-face borrowing. Privacy still depends on responsible data handling.
Flexible Repayment Schedules
Repayment periods differ between mobile credit products. Some offer options, while others use fixed payment schedules. Borrowers should choose terms matching expected income.
Factors to Consider Before Borrowing
Quick credit can become costly when repeatedly renewed. Reviewing cost, repayment, and privacy can reduce strain.
Interest Rates and Fees
Mobile credit may include interest, service charges, or other costs. Compare the total repayment amount before accepting funds. Repeated borrowing can make small charges significant.
Impact on Your Credit Score
Some lenders use or report information through credit reference bureaus. Missed payments may affect future credit assessments. Borrowers should confirm each provider's reporting policy.
Data Privacy and Security
Applications may involve identity, phone, bank, and transaction information. Kenya's Data Protection Act covers personal data processing. Borrowers should review privacy notices before sharing sensitive information.
Repayment Discipline
Instant access can make repeated borrowing easier. A budget and clear repayment plan can reduce debt pressure. Credit should address defined needs rather than routine overspending.
Safe Practices for Securing Mobile Loans
Safe borrowing starts with verifying providers and contract terms. Basic digital security habits can reduce fraud risks.
- Use official apps, websites, or mobile-money menus.
- Check the provider's current regulatory status.
- Never share PINs, passwords, or verification codes.
- Review permissions and privacy terms.
- Keep loan agreements and payment confirmations.
- Contact official support when terms remain unclear.
Legal and Regulatory Environment
The Central Bank of Kenya regulates covered digital credit providers. Its licensed-provider directory helps borrowers verify lenders.
Privacy Laws
Kenya's Data Protection Act governs personal information processing. The ODPC oversees data protection compliance and related rights. Borrowers should understand what lenders collect and why.
Complaint Resolution
Customers should first use the provider's complaint process. The relevant regulator or ODPC may assist where appropriate. Contracts and receipts can help document complaints.
Alternatives to Mobile Credit in Kenya
Mobile loans are not the only short-term funding option. SACCOs, microfinance institutions, savings, employer advances, or negotiated payments may suit borrowers.
Tips for Using Mobile Credit in Kenya
A few practical habits can make mobile borrowing safer and easier to manage. Focus on affordability, provider legitimacy, and clear repayment terms before accepting credit.
- Verify the lender through official CBK sources before applying.
- Compare the total repayment amount, including interest and fees.
- Borrow only what fits within your realistic monthly budget.
- Review app permissions and protect your personal financial data.
- Keep records of loan terms, payments, and support communications.
Conclusion
Mobile credit in Kenya can provide convenient short-term financing when used carefully. Borrowers should compare costs, verify providers, protect data, and understand repayment.
Checking licensing and complete loan terms can reduce unnecessary risk. Responsible borrowing means choosing credit that fits a realistic budget.